Ready to get started?
Easily integrate next-generation payments and financial data into any app. Build powerful products your customers love.
SHARE ARTICLE


 Share link copied!
There are seven ways a UK business can take a payment online, and they do not cost the same. A card through a gateway costs somewhere between 1.3% and 2.9% plus a fixed fee; a Direct Debit costs about 1%; a bank payment initiated through open banking costs 0.7% + 20p with Atoa; a manual bank transfer costs nothing per payment and a great deal in the time it takes to match. Most guides to the cheapest way to accept online payments list providers and their headline rates. This one separates the method from the provider first, because the rail you choose moves the cost more than the brand does, then puts the providers’ published 2026 rates side by side and works them through on a real month.
The seven methods, ranked by cost
| Method | How the customer pays | Typical UK fee (published, ex VAT) | Settlement | Chargebacks |
|---|---|---|---|---|
| Manual bank transfer | Keys your sort code, account number and amount into their banking app | £0 | Seconds over Faster Payments, but unconfirmed until you match it | None |
| Pay by Bank (open banking) | Taps a link or button, approves in their Bank app | 0.7% + 20p (Atoa) | Confirmed in seconds; paid out instantly or next day depending on settlement setup; within 48 hours on Shopify | None |
| Direct Debit | Signs a mandate; you collect | 1% + 20p, capped at £4 (GoCardless Standard) | 3 working days (Bacs) | Refund guarantee, not chargeback |
| Card via a gateway | Types card details at checkout | 1.5% + 20p (Stripe); 1.4% + 25p (Square); 1.3% + 20p (Atoa) | Provider schedule, typically 1–3 working days | Yes |
| Card via a platform | Card at a hosted checkout | 2% / 1.7% / 1.5% / 1.3% + 25p by plan (Shopify Payments) | 3 working days minimum in the UK | Yes |
| Digital wallet account | Pays from a PayPal balance | 2.9% + 30p (PayPal); 1.2% + 30p if card-funded | To balance at once; bank withdrawal about a day | Yes, plus disputes |
| Buy now, pay later | Splits the payment; you are paid in full | 4.99% + 30p (Klarna via Shopify) | Provider schedule | Provider carries default risk |
The order is the order of cost. The rest of the page explains why each sits where it does and when the cheapest is the wrong choice.
1. Manual bank transfer: free, and not free
A customer who pays by typing your bank details into their own app costs you nothing per transaction, which is why it remains the default for invoices. The cost is elsewhere. Every payment arrives with whatever reference the customer chose, somebody matches it to an invoice, and a share of them are late, short, or never sent because the customer put it off. For a business receiving 1,000 payments a month that matching is a part-time job, and the late ones are a working-capital cost that never shows on a fee statement. Bank transfer is the cheapest way to accept online payments only for a business with few, large, well-referenced invoices and a finance team with time.
2. Pay by Bank: the same rail with the keying removed
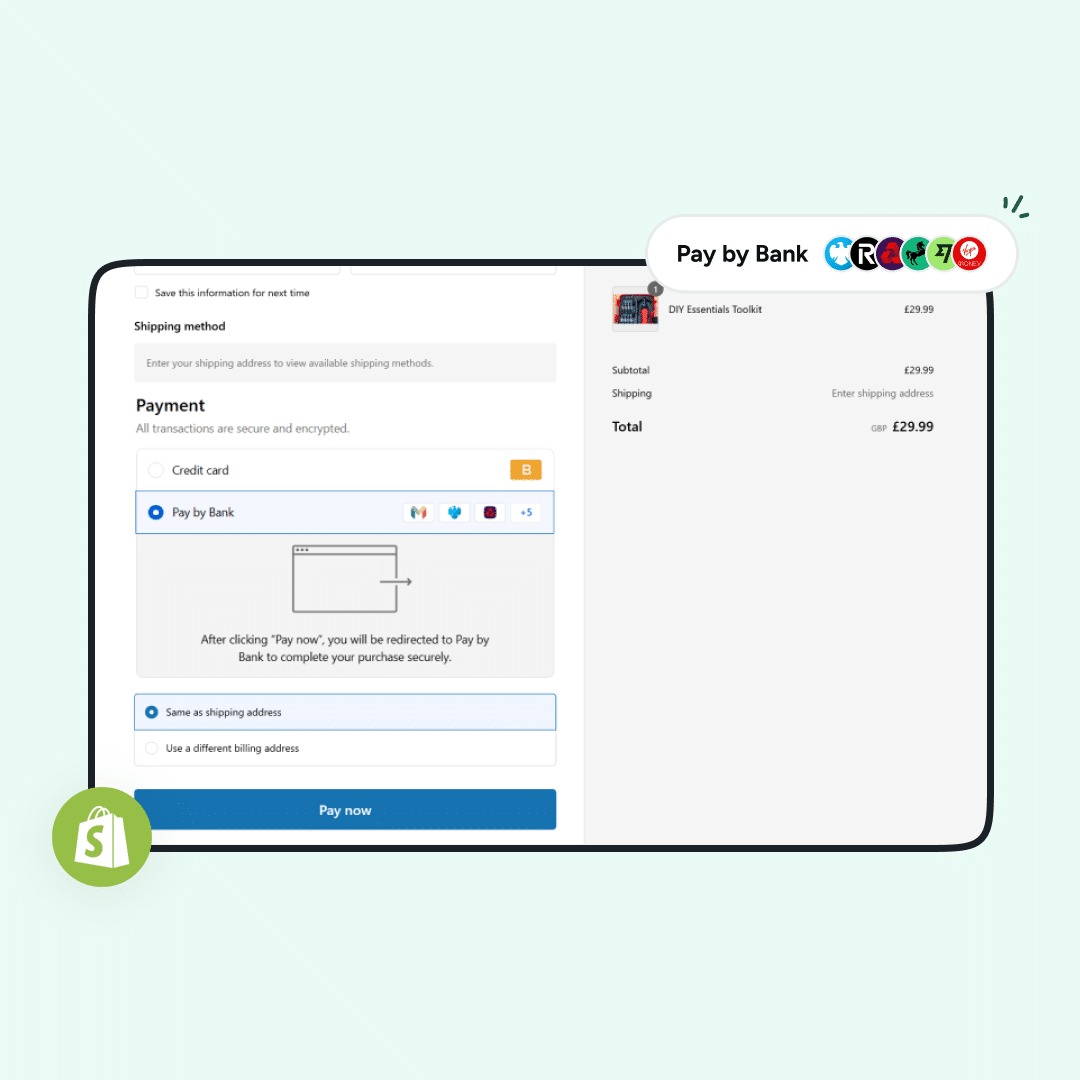
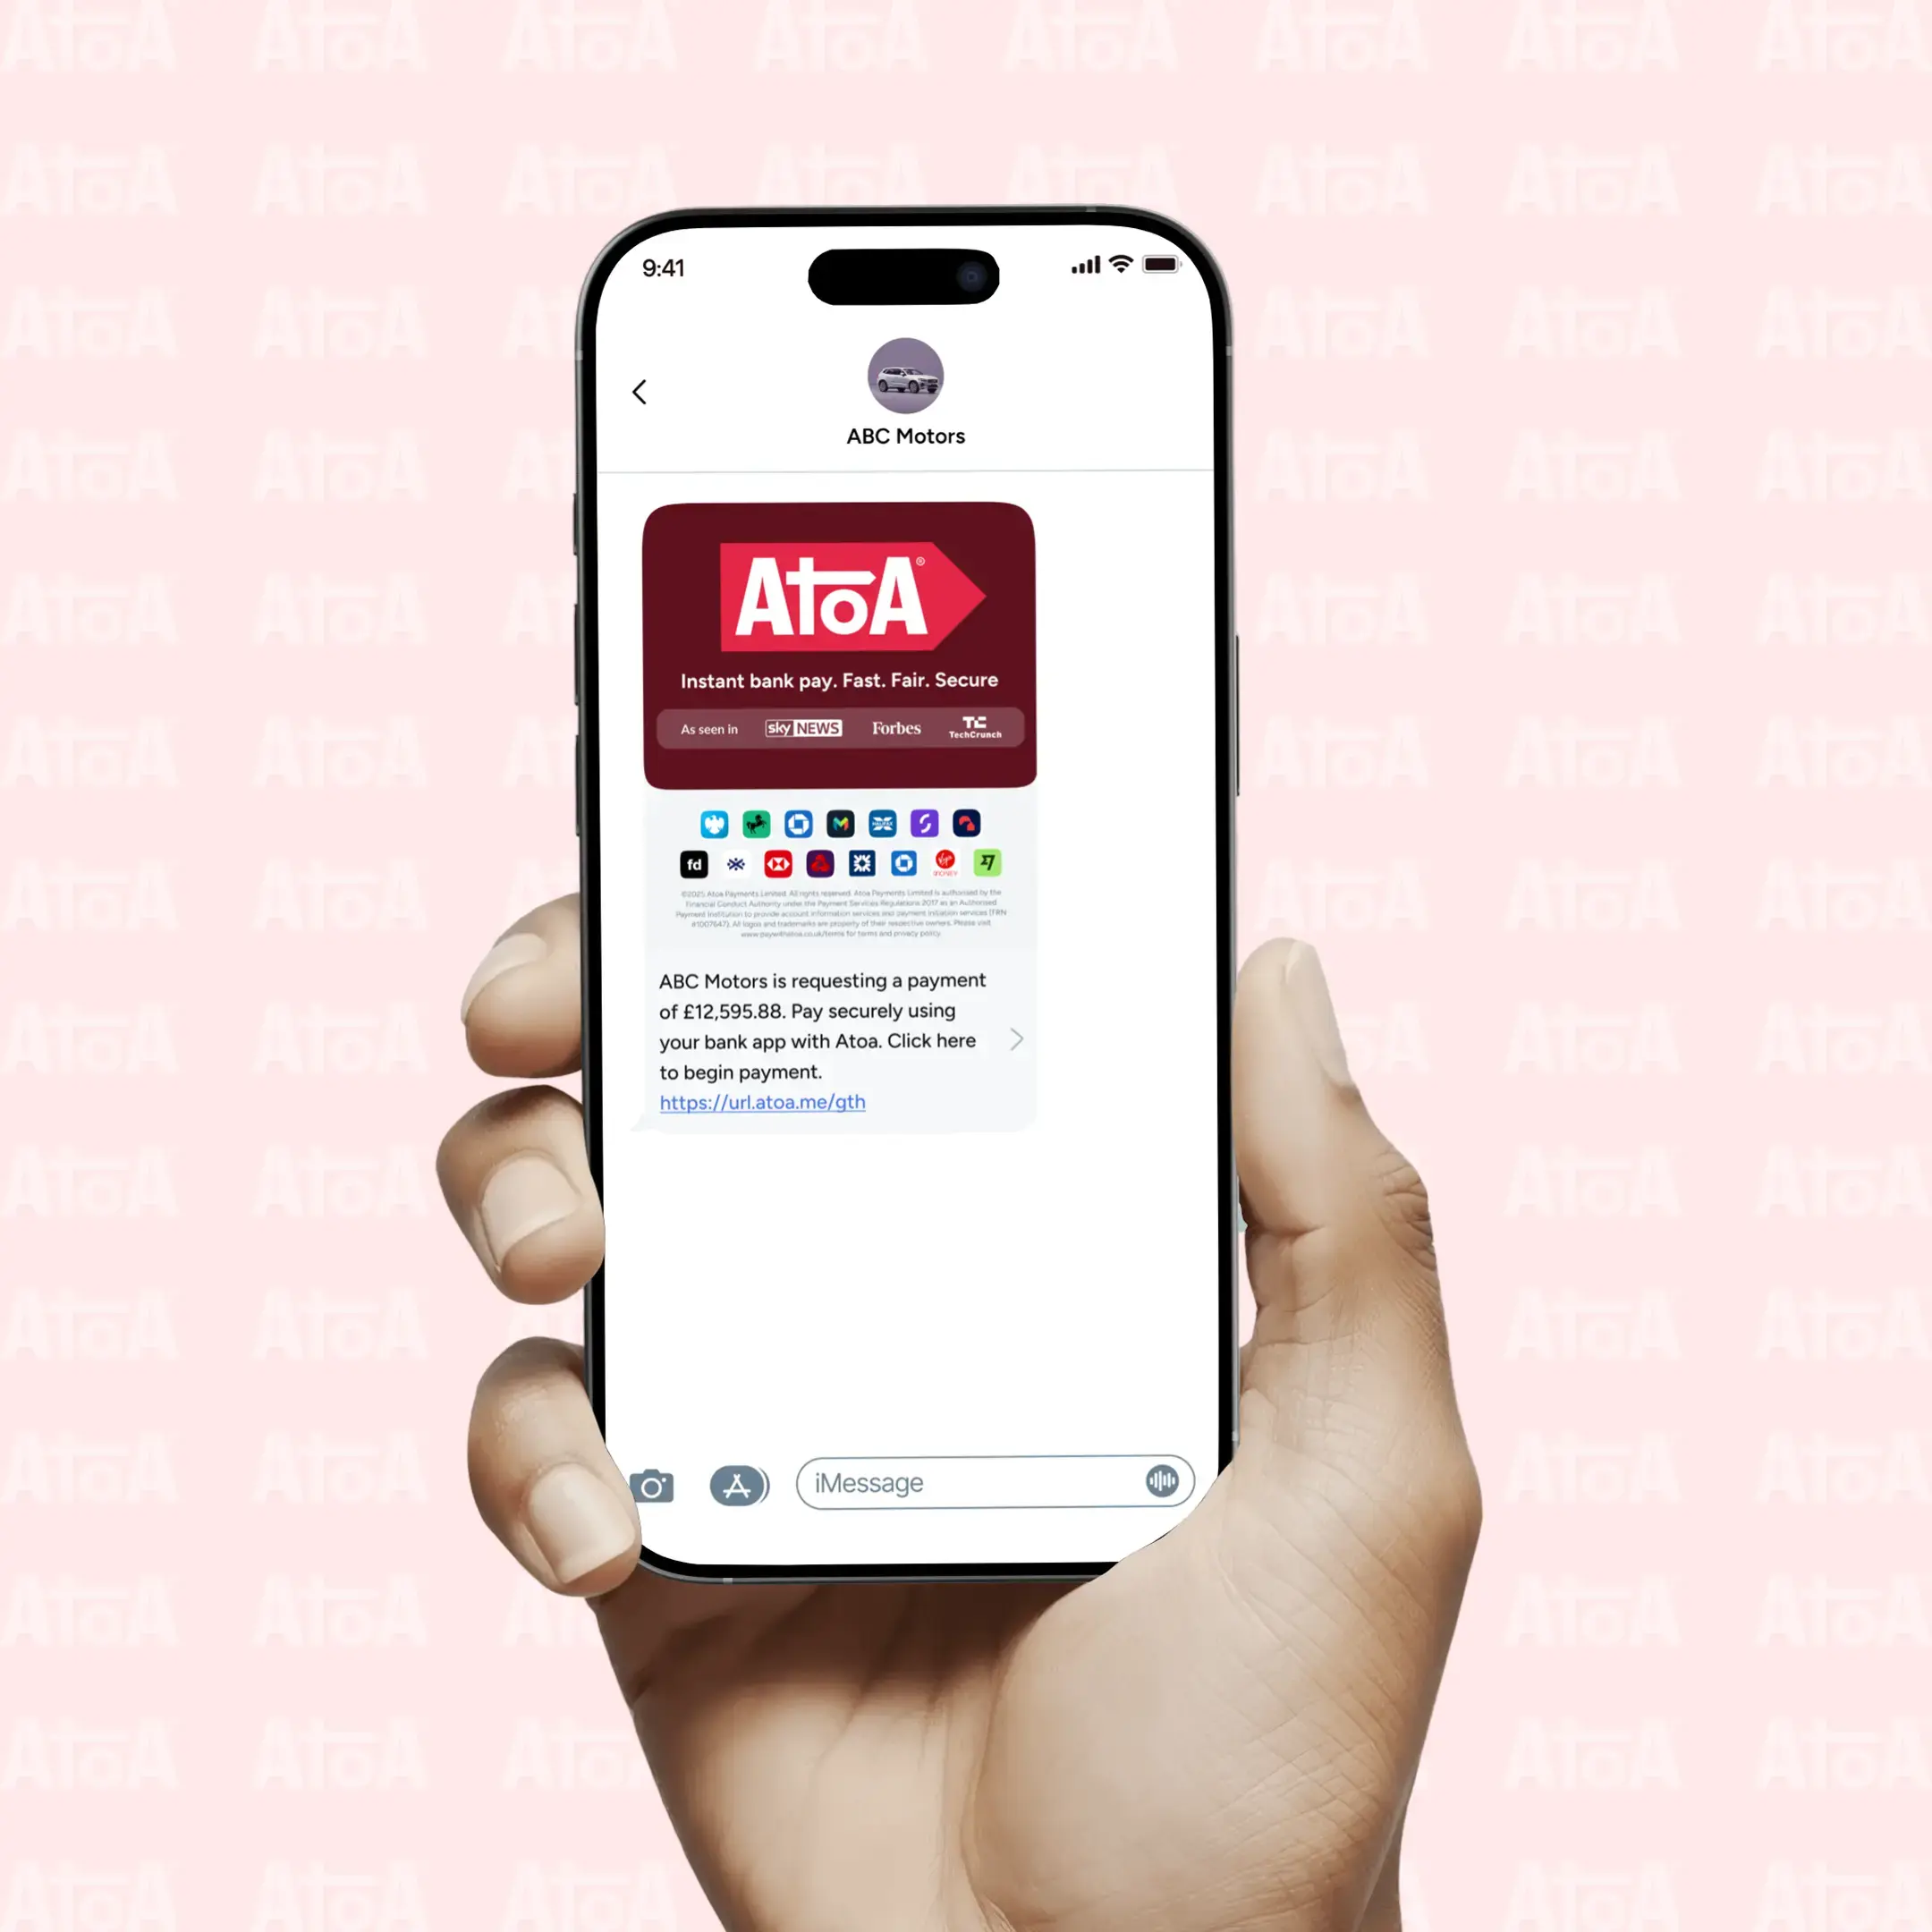
Pay by Bank is an account-to-account payment initiated through open banking. The customer taps a payment link, a checkout button or a QR code, their Bank app opens with the amount and payee already filled in, they approve with Face ID or a fingerprint, and the money moves over Faster Payments with a reference you set. There is no card, so there is no interchange, no scheme fee and no chargeback; a customer who is owed money asks for a refund, which you issue from the dashboard. Atoa charges 0.7% + 20p ex VAT online, falling with volume, and presents it on payment links sent by text or email, on online checkouts for Shopify, WooCommerce and Magento, and on invoices from Xero, QuickBooks and Sage. The constraints are real and worth stating: the customer needs a UK bank account and a phone in hand, there is a £15,000 per-payment limit, and on Shopify the payout is within 48 hours rather than seconds. Our comparison of Pay by Bank against card costs goes into the operational side.
3. Direct Debit: close on price, slow on cash
Direct Debit is a pull payment under the Bacs scheme: the customer signs a mandate once and you collect. GoCardless, the largest UK provider, publishes 1% + 20p per payment capped at £4 on its Standard plan, ex VAT, with 3 working days to settle and the Direct Debit Guarantee giving the payer an unconditional refund right (GoCardless pricing). For subscriptions and instalments it is hard to beat on price; for a one-off sale it is the wrong tool, because the customer has to set up a mandate and you wait three days to find out whether the money came. Open banking’s answer to recurring collection, variable recurring payments, is arriving commercially in the UK with Atoa among the providers in the pilot.
4. Cards through a gateway: the benchmark everyone quotes
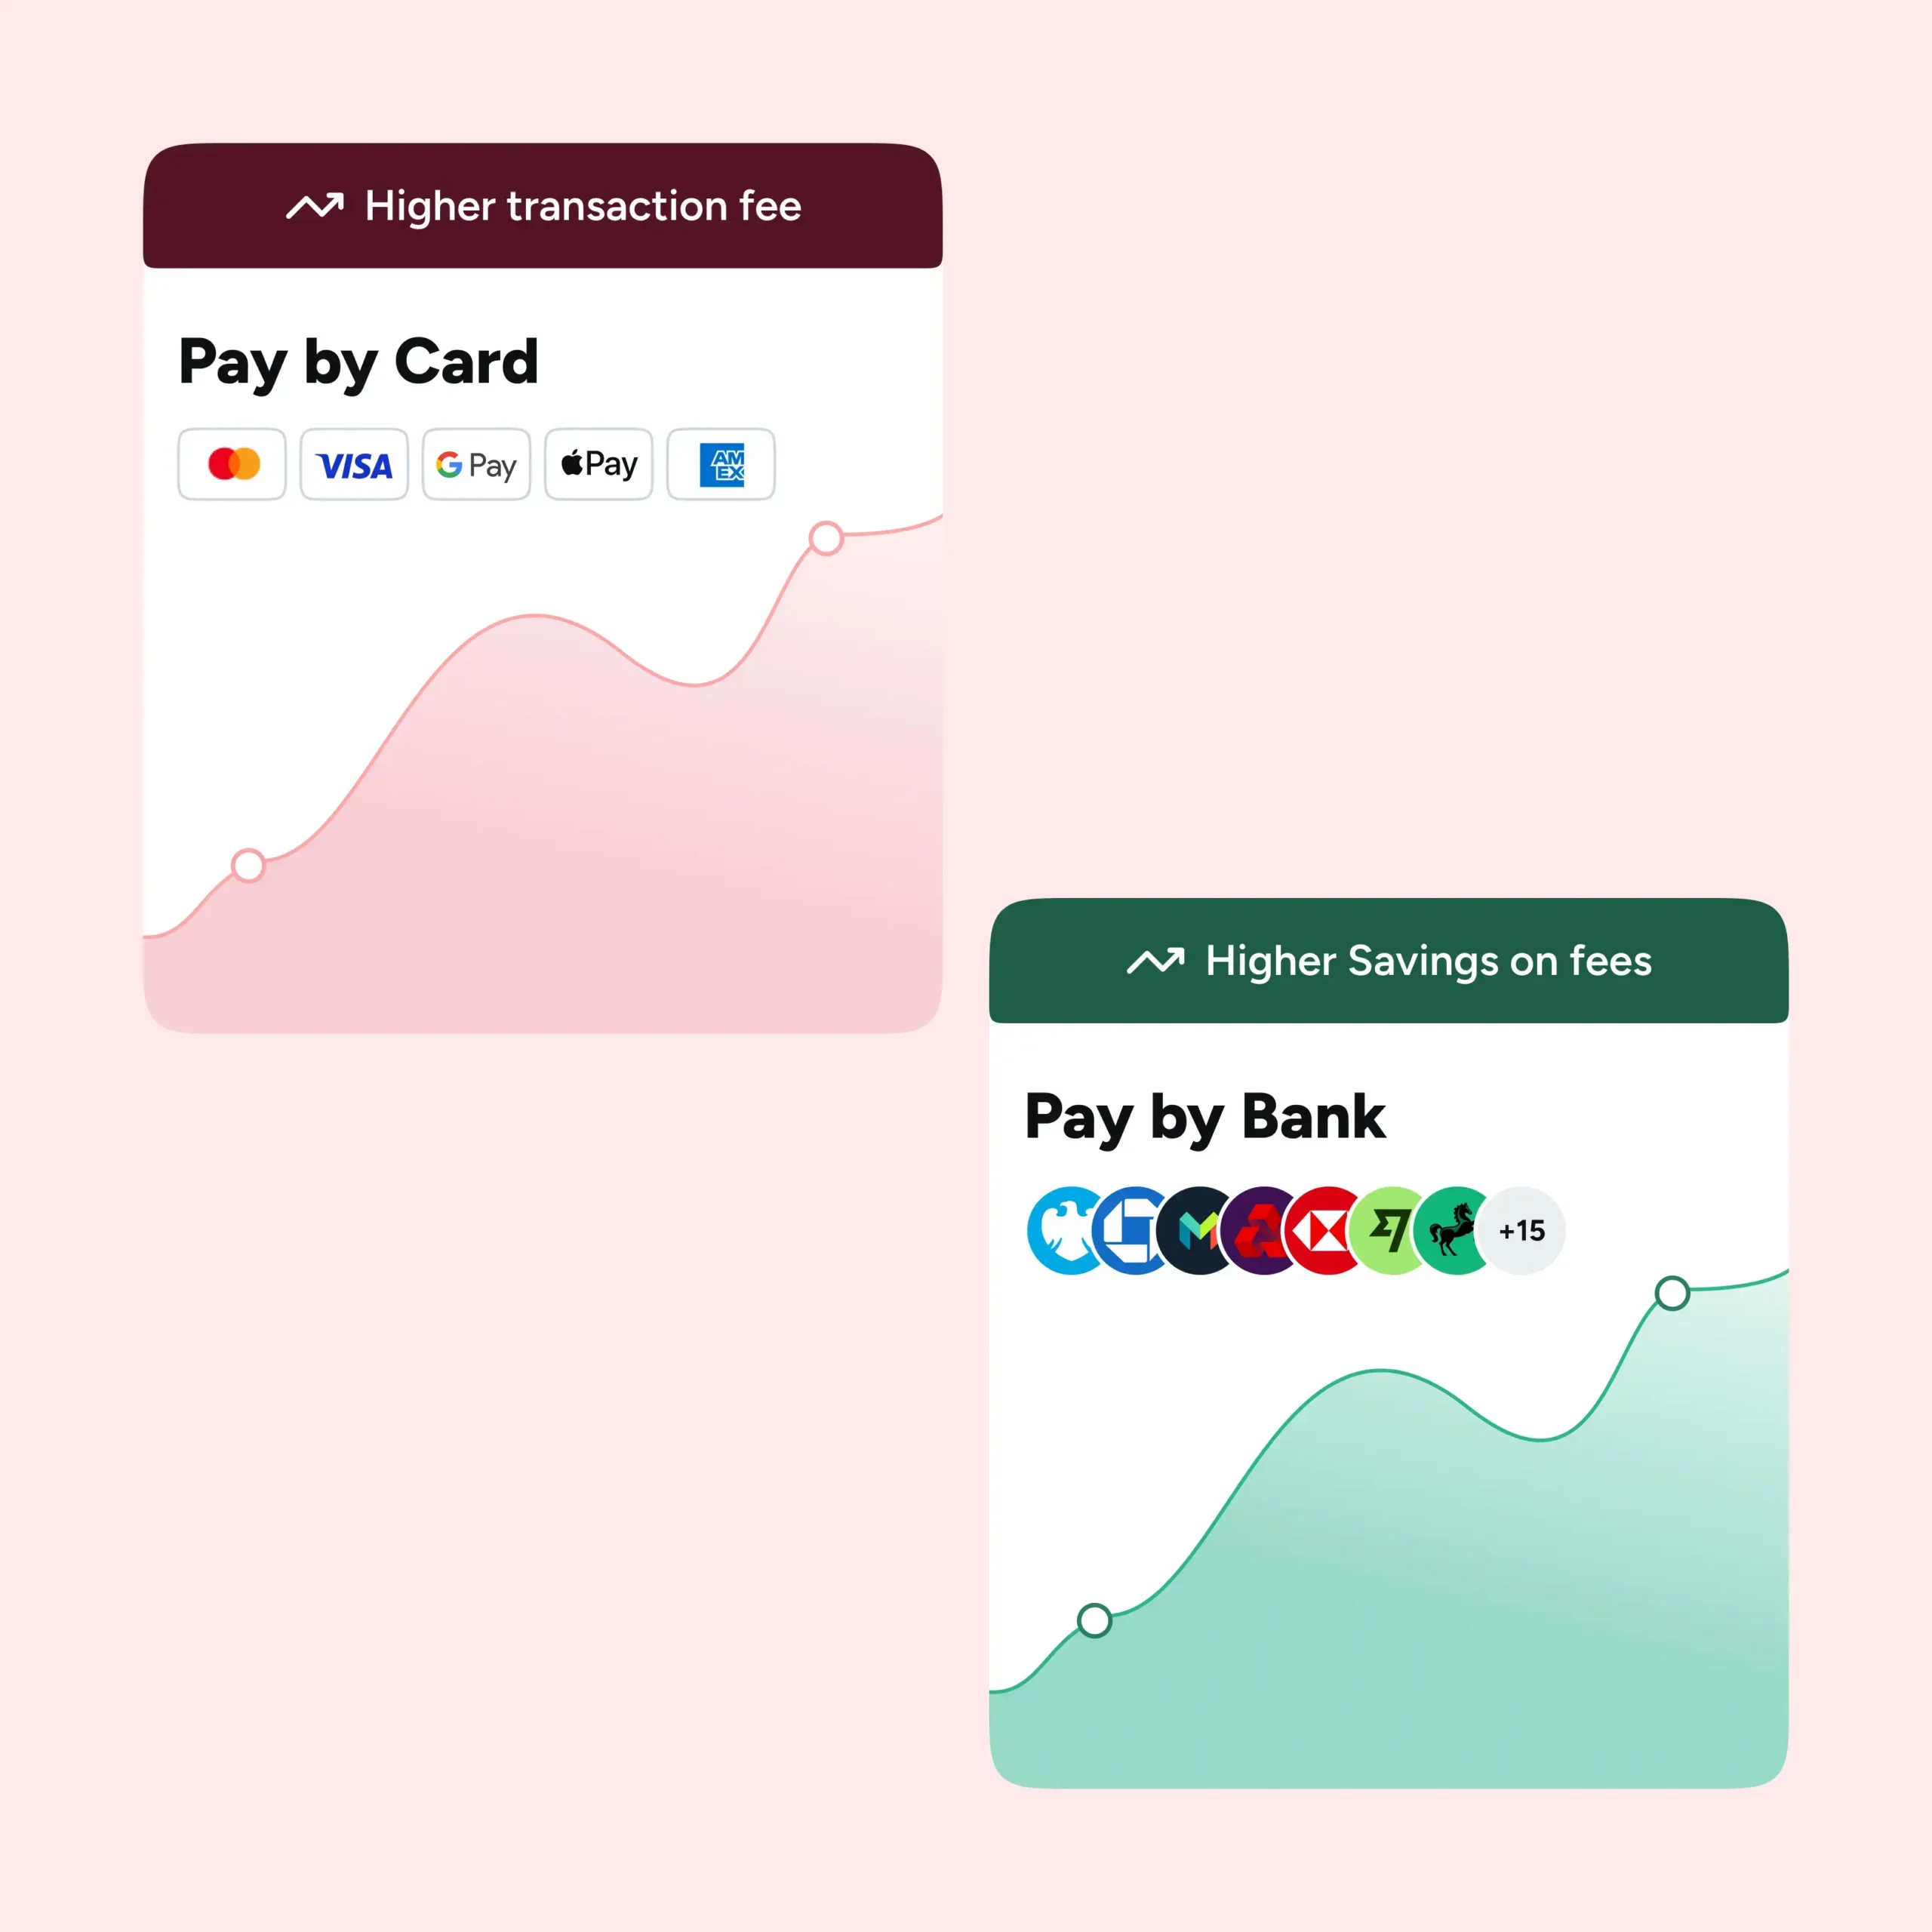
Stripe publishes 1.5% + 20p for standard UK cards, 2.8% + 20p for premium UK cards, 2.5% + 20p for EEA cards and 3.15% + 20p for other international cards, plus 2% where currency conversion is needed, with no monthly fee (Stripe UK pricing). Square publishes 1.4% + 25p for online payments (Square UK pricing). Atoa’s own card option, acquired by Rapyd, is 1.3% + 20p online. The reason online card fees sit above in-person ones is that a card-not-present payment carries more fraud risk and the acquirer prices it in; the reason they sit above Pay by Bank is interchange (capped at 0.2% debit and 0.3% credit for consumer cards under the Interchange Fee Regulation) and scheme fees, which a bank payment does not carry at all. Our complete guide to card payment processing fees breaks the card side down line by line.
5. Cards through a platform: convenient, and priced by plan
Shopify Payments charges 2% + 25p on Basic, 1.7% + 25p on Grow, 1.5% + 25p on Advanced and 1.3% + 25p on Plus for standard UK cards, with Amex and international cards from 3.1% down to 2.3% + 25p (Shopify UK pricing), and settles in a minimum of three business days in the UK. It carries no extra Shopify fee, which is the point: every other gateway on Shopify pays a 2% / 1% / 0.6% / 0.2% transaction fee on top of its own rate. Our comparison of Shopify payment gateways works that through by plan.
6. PayPal: recognised, and the dearest mainstream option
PayPal’s UK merchant rate is 2.9% + 30p for payments funded from a PayPal balance or account, and 1.2% + 30p for card payments taken through PayPal’s own checkout (PayPal UK merchant fees). Funds land in the PayPal balance immediately and reach your bank in about a business day. It converts customers who will not type a card number, and it is the one third-party method Shopify exempts from its transaction fee, so it earns a place as a second button. As a primary method it is the most expensive line in the table apart from BNPL.
7. Buy now, pay later: a conversion tool, not a payment rail
Klarna through Shopify is 4.99% + 30p; Adyen’s published UK Klarna rate is $0.13 + 4.99% + 20p (Adyen pricing). You are paid in full and the provider carries the credit risk. That is the right trade on a £600 basket where the alternative is no sale; it is the wrong default for everyday payments. Atoa offers Pay Later at the point of sale through Abound, with Atoa as introducer and no credit risk on Atoa’s balance sheet; it sits alongside Pay by Bank and cards rather than replacing them.
What each method costs on £50,000 a month
The example is 1,000 online payments averaging £50, all from UK customers with UK cards, using the providers’ published standard rates on 25 September 2026, ex VAT. Amex, international cards and currency conversion would raise every card row.
| Method and provider | Fee per payment | Monthly fee on £50,000 | Settlement |
|---|---|---|---|
| Manual bank transfer | £0 | £0 (plus matching time and late payments) | Seconds, unconfirmed |
| Pay by Bank, Atoa | 0.7% + 20p | £550 | Seconds to 48 hours by channel |
| Direct Debit, GoCardless Standard | 1% + 20p, cap £4 | £700 | 3 working days |
| Card, Atoa | 1.3% + 20p | £850 | Provider schedule |
| Card, Square online | 1.4% + 25p | £950 | Provider schedule |
| Card, Stripe standard UK | 1.5% + 20p | £950 | Rolling, provider schedule |
| Card, Shopify Payments Grow | 1.7% + 25p | £1,100 | 3 business days minimum |
| PayPal, PayPal-funded | 2.9% + 30p | £1,750 | Balance at once; bank about a day |
| Klarna via Shopify | 4.99% + 30p | £2,795 | Provider schedule |
Three things follow. The rail matters more than the brand: the three card gateways land within £100 of each other, and the gap between any of them and Pay by Bank is £400 to £550 a month before a single chargeback. The fixed fee matters more than the percentage on small baskets: at £50 a payment the 20p is 0.4% on its own, and on a £15 basket it is 1.3%, so a business with small tickets should weight the pence, not the percent. And the cheapest method is not always available: a customer abroad, a customer who wants credit, or a £20,000 invoice above the Pay by Bank limit needs a card or a transfer, which is why the right answer for most businesses is Pay by Bank first with cards behind it, not one or the other.
How to accept online payments with the lowest fees, in practice
Put the lowest-cost method first wherever the customer pays: on the payment link you text after a call, at the top of the checkout, on the invoice’s pay button. Keep cards available without promoting them. Do not offer a discount for paying by bank; the ordering does the work, and Atoa’s customers move the bulk of their volume across without incentives. Reconcile automatically, because a fee saving that creates manual matching is not a saving. Check the fixed fee against your average basket. And read the settlement column as carefully as the fee column: three days of float on £50,000 a month is £5,000 permanently out of your account. For the tactics beyond method choice, our guide to reducing payment processing fees covers negotiation, card mix and reconciliation. To see the numbers on your own volume, book a demo.
Frequently asked questions
What is the cheapest way to accept online payments in the UK?
A bank payment. A manual bank transfer has no transaction fee but costs matching time and late payments; Pay by Bank through Atoa keeps the same rail, pre-fills the details and costs 0.7% + 20p ex VAT with no chargebacks. Cards through Stripe, Square or Shopify Payments run from 1.3% to 2% plus 20–25p, and PayPal 2.9% + 30p.
Which payment methods have near-instant settlement and no chargebacks?
Pay by Bank. The customer approves the payment in their own Bank app and the money moves account to account over Faster Payments, so there is no card scheme to run a chargeback and the payment is confirmed in seconds. Manual bank transfers also have no chargebacks but are not confirmed until you match them.
Can I accept payments online without transaction fees?
Only by manual bank transfer, where the customer keys your details themselves. Every provider that confirms, reconciles or protects the payment charges per transaction; the lowest published UK rates are 0.7% + 20p for Pay by Bank and 1% + 20p capped at £4 for Direct Debit.
What is the cheapest way to take card payments online?
Among published UK rates, Atoa’s card option at 1.3% + 20p, Square at 1.4% + 25p and Stripe at 1.5% + 20p for standard UK cards are the lowest pay-as-you-go online card rates; Shopify Payments matches them only on its Advanced and Plus plans. In-person card rates are lower than online because card-present payments carry less fraud risk.
How much does it cost to accept online payments?
On £50,000 a month across 1,000 payments, published UK rates give about £550 with Pay by Bank, £700 with Direct Debit, £850 to £1,100 with a card gateway or Shopify Payments, £1,750 with PayPal and £2,795 with Klarna, all ex VAT and before chargebacks or currency conversion.
Which payment gateway has the lowest transaction fees in the UK?
For cards, Atoa (1.3% + 20p), Square (1.4% + 25p) and Stripe (1.5% + 20p) publish the lowest standard online rates. For the lowest fee overall, a gateway that offers Pay by Bank, such as Atoa at 0.7% + 20p, undercuts every card rate because it carries no interchange or scheme fee.
Sources
- Stripe, UK pricing, 25 September 2026
- Square UK, pricing
- Shopify, UK pricing and UK payout times
- PayPal, UK merchant fees
- GoCardless, pricing
- Adyen, pricing
- Payment Systems Regulator, Interchange Fee Regulation
- Atoa, pricing, Pay by Bank and Shopify pages
SHARE ARTICLE
Share link copied!