Ready to get started?
Easily integrate next-generation payments and financial data into any app. Build powerful products your customers love.
SHARE ARTICLE


 Share link copied!
B2B payment solutions are the methods and platforms businesses use to collect money from other businesses such as Bacs, Faster Payments, CHAPS, Direct Debit, commercial cards and Pay by Bank through open banking, plus the invoicing and reconciliation software around them. For UK businesses invoicing on credit terms, Pay by Bank is the lowest-fee option, from 0.7% + VAT with Atoa, and which is settled in seconds.
Imagine a wholesaler in Leeds sends 400 invoices a month to trade customers. Half are paid by Bacs a few days late, a quarter by card at fees that quietly cost more than the delivery, and the rest arrive as bank transfers with the wrong reference that someone in finance has to match by hand. That is what B2B payments solution look like for most UK businesses, and it is why the choice of payment solution decides the cash-flow to a business.
This guide explains what B2B payment solutions are, compares the payment methods UK businesses actually use, looks at the main providers, and how to choose the best among them. It is written for established businesses that invoice other businesses: wholesalers and distributors, trade suppliers, professional services firms, multi-site operators and dealerships selling to the trade.
What Are B2B Payments?
B2B (business-to-business) payments are transfers of money between two companies for goods or services, as opposed to B2C payments from a consumer. A distributor paying a manufacturer, a restaurant group settling its drinks supplier, a law firm collecting fees from a corporate client, or a garage buying parts from a trade counter are all B2B payments.
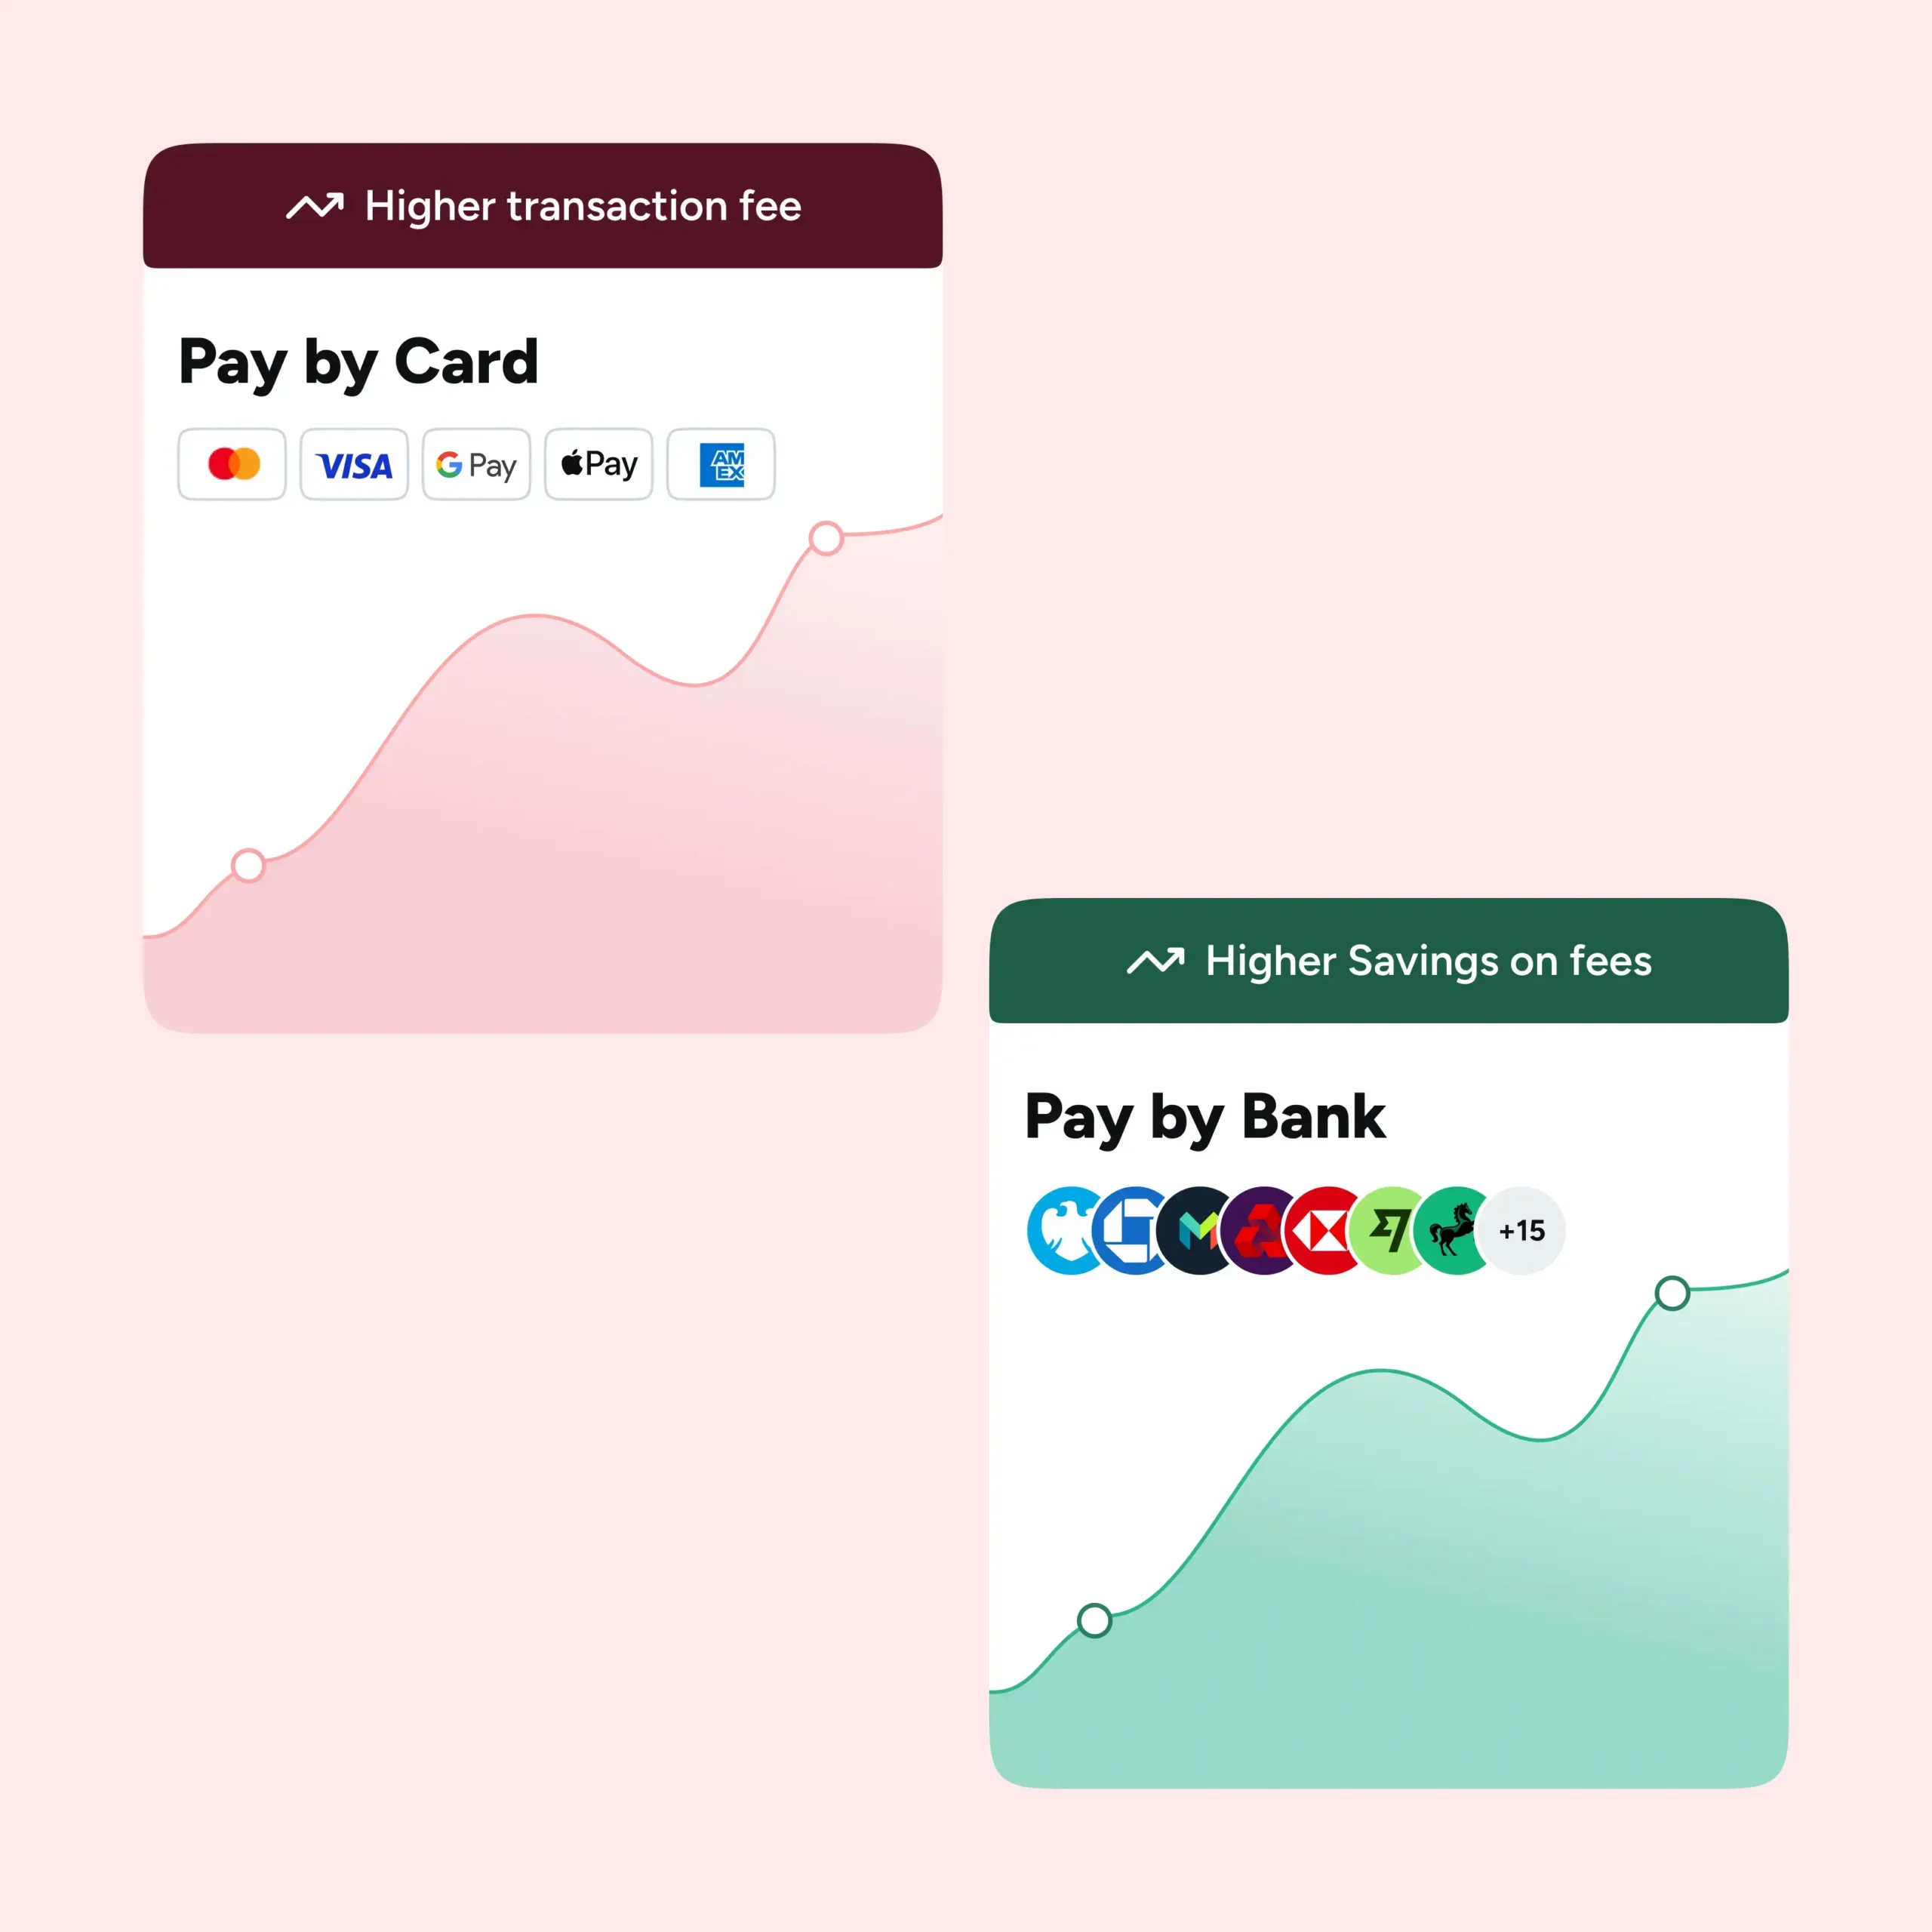
They differ from consumer payments in three ways that matter. Values are higher, often thousands of pounds per invoice rather than tens. They run on credit terms, typically 30 days, so the payment is separated from the sale and has to be chased and reconciled. And the fee structure is different: commercial cards are not covered by the UK interchange fee caps that apply to consumer cards, so card acceptance on B2B invoices is usually more expensive than on a retail sale.
B2B Payment Methods Used in the UK
UK businesses use a mix of bank transfers, Direct Debit, cards and newer Open Banking payments to settle invoices. The method often depends on whether the payment is planned, urgent, recurring or tied to a specific invoice.
Bacs
Bacs is commonly used for payroll, supplier payments and other scheduled transfers. It follows a three-working-day cycle, which works well when payments can be planned in advance. For businesses collecting invoices, the timing remains with the payer, so receiving payment can still involve waiting and chasing.
Faster Payments
Faster Payments allows money to move between UK bank accounts in near real time and operates 24/7. It is useful when an invoice needs paying quickly, although a standard bank transfer still relies on the customer entering the correct account details and payment reference. A missing reference can leave the finance team working out which invoice the payment belongs to.
CHAPS
CHAPS is mainly used for high-value payments that need to settle on the same working day. It is more suited to transactions such as property purchases, large stock orders or major supplier payments than everyday invoices. Banks may charge a fixed fee for sending a CHAPS payment.
Direct Debit
Direct Debit allows a business to collect payments from a customer’s bank account after receiving a mandate. It is particularly useful for recurring B2B payments such as subscriptions, retainers, rentals and regular service charges. Collections are covered by the Direct Debit Guarantee, which gives customers protection if a payment is taken incorrectly.
Commercial cards
Business credit, debit and commercial cards can be convenient when buyers want to pay an invoice immediately. For the seller, the cost can include interchange, scheme fees and the payment provider’s margin. Card payments can also be challenged through the chargeback process, which is worth considering for higher-value B2B transactions.
Pay by Bank through Open Banking
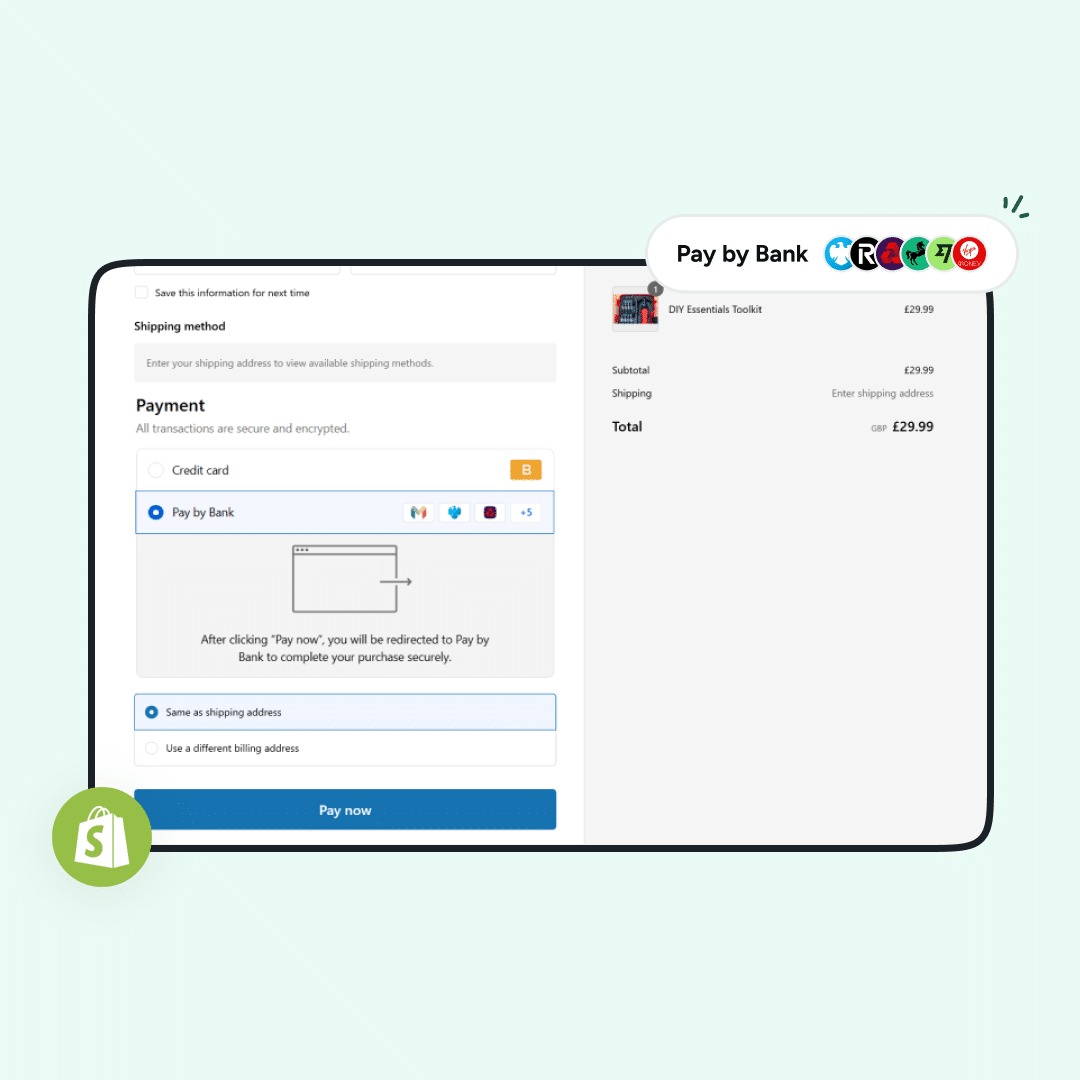
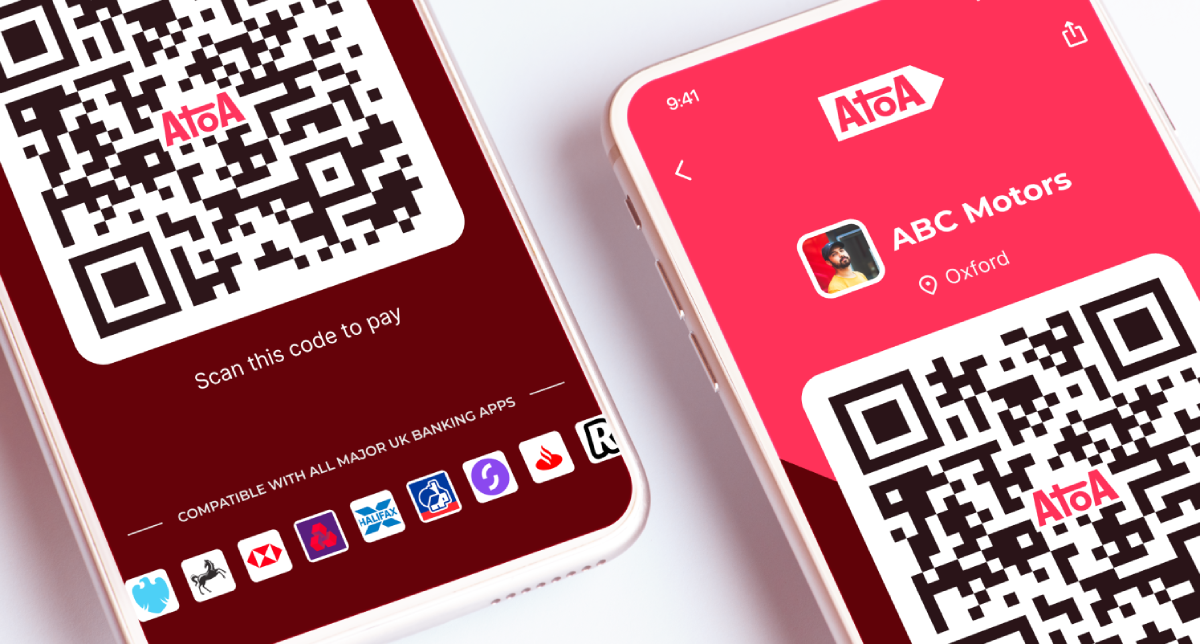
Pay by Bank gives customers a more structured way to make a bank payment. Instead of copying account details from an invoice, the buyer follows a payment link or scans a QR code, selects their bank and approves the payment in their banking app. The transaction can carry the correct payment reference with it, making it easier to match the money received with the relevant invoice. You can read more about the process in our Open Banking payments guide.
Digital wallets
Apple Pay and Google Pay can be useful when B2B customers pay through an online checkout. Although the checkout experience is quicker, these are generally card-based payments underneath, so the merchant’s usual card processing costs still apply. Our digital and mobile wallets guide explains how they work and where they fit.
Comparison of B2B Payment Methods
| Method | Cost to the seller | Settlement | Reconciliation | Chargebacks |
|---|---|---|---|---|
| Bacs | Low or none | 3 working days | Manual, reference often missing | No |
| Faster Payments (manual) | None | Seconds | Manual, depends on payer typing the reference | No |
| CHAPS | Fixed bank fee per transfer | Same day | Manual | No |
| Direct Debit | Provider fee per collection | 3 to 5 working days | Automatic, mandate-based | Refundable under DD Guarantee |
| Commercial cards | Typically 1.5% to 3.4% all-in, higher for business cards (PSR, 2021 card-acquiring market review) | 1 to 3 working days | Via acquirer statement | Yes |
| Pay by Bank with Atoa | From 0.7% + VAT | Seconds | Automatic, reference and invoice matched, synced to Xero, QuickBooks or Sage | No |
How B2B Payment Processing Works?
The seller raises an invoice with the amount, terms and a way to pay. The buyer pays by whichever method the invoice allows; on a bank transfer they key the details themselves, on a Pay by Bank invoice they click the link and approve in their Bank app. The provider processes the payment, the funds land in the seller’s account, and the payment is matched to the invoice in the accounting system, either by a person or automatically. The gaps between those steps are where cost and delay accumulate. A manual transfer with a mistyped reference can sit unreconciled for a week. A card payment can be reversed weeks later. A Pay by Bank payment is confirmed, referenced and reconciled in one motion.
B2B Payment Providers in the UK
Most B2B payment providers were built for one job: GoCardless for Direct Debit, Stripe and Worldpay for card acquiring, your bank for outbound transfers. That leaves a business stitching two or three of them together and reconciling by hand. Atoa covers collection end to end on one platform, and on the four numbers that matter to a finance team it comes out ahead.
| Atoa | GoCardless | Stripe | Worldpay | Your bank | |
|---|---|---|---|---|---|
| Bank payments (open banking) | Yes, Pay by Bank from 0.7% + VAT | Direct Debit and open banking | Limited | Limited | Manual transfer only |
| Card payments | Yes, from 1.3% | No | Yes | Yes | No |
| Recurring / variable payments | Yes, Variable Recurring Payments | Direct Debit (fixed mandate, 2 to 3 working days) | Card subscriptions | Card subscriptions | Standing order / Direct Debit |
| Settlement | Seconds over Faster Payments | Working days | Working days | Working days | Same day (Faster Payments) |
| Chargebacks | None on Pay by Bank | Indemnity claims possible | Yes | Yes | None |
| Invoice collection | Pay now link on Xero, QuickBooks and Sage invoices, auto-reconciled | Via accounting add-ons | Stripe Invoicing | Limited | Manual matching |
| Pay Later for larger orders | Yes, via Abound (Atoa is the introducer) | No | Third-party BNPL | Third-party BNPL | No |
| Best fit | UK businesses that invoice other businesses and want faster, lower-fee, reconciled collection with cards as fallback | Subscription or retainer revenue on fixed schedules | High-volume online card sales with a developer team | Enterprise card processing, including international | Outbound supplier payments and payroll |
Fees and settlement times for other providers vary by plan and volume; check each provider’s current pricing page. Atoa’s rates are on our pricing page.
Using B2B Payment Software
The software layer around payments is where the time goes back. Look for invoice creation and tracking, automated reminders before and after the due date, approval workflows for larger payments, and accounting integration so that every payment posts against the right invoice without retyping. Our guide to automated payment systems covers the options. With Atoa, a Pay by Bank link is added to invoices raised in Xero, QuickBooks or Sage, payment reminders go out by SMS or email, and settled payments reconcile automatically. The full list of connections is on our integrations page.
What to Look For in a B2B Payment Platform
Most businesses end up running three systems that do not talk to each other: an accounting package that raises the invoice, a gateway that takes the payment, and a spreadsheet that tracks who has paid. The platform you choose decides how much of that gap closes on its own.
Five things separate a platform that saves time from one that adds a login. It has to put a way to pay on the invoice itself rather than leaving the buyer to find your bank details. It has to chase, with reminders going out before and after the due date without anyone remembering to send them. It needs approval rules for payments above a threshold, because finance teams will not route five-figure invoices through a tool that has none. It must write back to your accounting software so the payment posts against the right invoice. And it should handle more than one payment method, because a platform that only does cards or only does Direct Debit leaves you running a second one alongside it.
A B2B payment gateway is the narrowest of these options. It takes the payment and stops there, which works if your invoicing and reconciliation are already handled elsewhere. For most invoicing businesses the gateway is the part they already have and the reconciliation is the part they do not.
Open Banking as a B2B Payment Solution
Open banking gives a regulated provider permission to initiate a payment straight from the buyer’s bank account. For B2B invoices that solves the three problems above at once. Cost: no card network, so the fee is a fraction of a commercial-card rate. Speed: Faster Payments, so funds are confirmed in seconds and available for wages and stock the same day. Reconciliation: the reference and invoice number travel with the payment, so finance stops matching by hand. It also removes chargeback risk on high-value invoices, and because the buyer authorises in their own Bank app with biometrics, it meets Strong Customer Authentication without the seller storing any bank or card data.
Atoa’s standard single-payment limit is £15,000, with higher limits available on request for businesses that regularly invoice above that. Recurring B2B collection by bank is the next step in the UK, and Atoa’s recurring payments page covers where that stands.
B2B Payouts: Paying Suppliers and Partners
Everything above covers money coming in. Paying money out is a separate problem with a separate set of tools, and it is worth being clear about which one you are solving.
For routine supplier payments and payroll, Bacs through your business bank account remains the default. It is low cost, it handles batches, and the three working day cycle is predictable enough to plan around. Faster Payments is the option when something has to move today, subject to your bank’s own limit. CHAPS covers the occasional high-value transfer where guaranteed same-day settlement justifies a fixed fee. Dedicated payout platforms become worth paying for when you are sending hundreds of payments a month, paying contractors or partners on a schedule, or settling across currencies.
Choosing the Right B2B Payment Solution
Four questions do most of the work. How much do you pay per £100 collected, including card fees, fixed pence, monthly platform charges and the cost of chasing? How quickly do you need the money in the account? How much of your team’s time goes on matching payments to invoices? And does the solution connect to the accounting software you already run, rather than adding another system? For an invoicing business, the answers usually point to Pay by Bank on the invoice as the default, cards as the fallback for buyers who insist, and Direct Debit for anything recurring.
Late payment is the other cost to price in. UK law lets you charge statutory interest at 8% above the Bank of England base rate on overdue commercial invoices (GOV.UK), but few businesses want to. A payment method that gets the invoice paid the day it lands is worth more than the interest you could charge on one that does not.
If your platform collects payments on behalf of multiple suppliers, see our guide to marketplace payment solutions for how seller onboarding, split payments and FCA authorisation apply.
How Secure Are B2B Payments?
B2B fraud rarely looks like fraud. The common pattern is an email that appears to come from a supplier, asking for future invoices to be paid to new bank details, and it works because a bank transfer is exactly what the buyer expected to make. Once the money has gone, recovering it depends on the receiving bank acting fast.
Card payments carry the opposite problem. The buyer is protected and the seller is not, so a commercial card payment on a five-figure invoice can be reversed through a chargeback weeks after the goods have shipped.
Pay by Bank closes both gaps at the seller’s end. The buyer does not type your bank details, because the payment is initiated against your verified account through a regulated provider, so there is nothing for a fake email to redirect. The buyer authorises inside their own Bank app with Face ID, a fingerprint or a passcode, which satisfies Strong Customer Authentication. And because no card scheme is involved, the payment cannot be charged back. Whichever method you use, check the provider is FCA-authorised.
Where B2B Payments Are Heading?
Three trends will shape the next few years. Open banking is moving from consumer checkouts into invoicing and recurring collection. Commercial Variable Recurring Payments went live on 2 June 2026 under the UK Payments Initiative, an industry-owned company backed by 31 organisations including Nationwide, NatWest Group, Mastercard etc. with coverage aimed at around 75% of UK current accounts. The first wave is restricted to utilities, telecoms and rail, regulated financial services, e-money funding, government payments and registered charities, with a second wave expected in late 2026. Automation is removing the reconciliation step altogether as payment data flows straight into accounting systems. And instant settlement is becoming the expectation rather than the premium, which changes how businesses manage working capital.
Key Takeaways
For an established UK business that invoices other businesses, Pay by Bank on the invoice is now the lowest-fee, fastest-settling and easiest-to-reconcile way to get paid, with cards kept as a fallback and Direct Debit for recurring billing. Choose a provider on total cost per £100 collected, settlement speed, reconciliation and accounting integration. With Atoa, that means Pay by Bank from 0.7% + VAT and cards from 1.3% on one platform, connected to Xero, QuickBooks and Sage, with a 7-day free trial to start and pricing that is published, not quoted.
FAQs
What are B2B payment solutions?
B2B payment solutions are the methods and platforms businesses use to pay and get paid by other businesses: Bacs, Faster Payments and CHAPS bank transfers, Direct Debit, commercial cards, and Pay by Bank through open banking, together with the invoicing and reconciliation software around them.
What is the cheapest way to take B2B payments in the UK?
A manual bank transfer costs the seller nothing but is slow to reconcile. Among automated methods, Pay by Bank is the lowest-fee option, from 0.7% + VAT with Atoa, compared with 1.5% to 3.4% all-in for cards and more for commercial cards.
How long do B2B payments take?
Bacs takes three working days, Direct Debit three to five, cards one to three working days to settle, CHAPS same day, and Faster Payments or Pay by Bank seconds.
Are B2B payment solutions secure?
Bank transfers and Pay by Bank are authorised by the payer inside their own banking, with Pay by Bank using Face ID, fingerprint or passcode, so no card or account details are shared with the seller. Card payments rely on encryption and 3-D Secure and carry chargeback risk. Choose FCA-authorised providers.
Can B2B payment solutions integrate with my accounting software?
Yes. Atoa connects to Xero, QuickBooks and Sage so invoice payments are matched automatically; GoCardless and Stripe also offer accounting integrations. Check the integration covers reconciliation, not just invoice creation.
What is a B2B payment gateway?
A B2B payment gateway is the component that takes the payment at the point the buyer chooses to pay, encrypts the details and passes them on for processing. It handles the transaction and nothing else, so invoicing, chasing and reconciliation stay wherever they already live. A full B2B payment platform covers all four.
Does Atoa handle B2B payouts to suppliers?
No. Atoa covers payment collection, meaning Pay by Bank and card payments on your invoices, links and checkout. Outbound supplier payments and payroll run through your business bank account by Bacs, Faster Payments or CHAPS, or through a dedicated payouts platform.
Is there a limit on B2B payments by Pay by Bank?
Atoa’s standard limit is £15,000 per payment, with higher limits available on request. Faster Payments itself supports up to £1 million per payment at most UK banks.
Sources
- Pay.UK, Faster Payment System
- Payment Systems Regulator, card-acquiring market review
- GOV.UK, Late commercial payments: charging interest and debt recovery
- Open Banking Limited, open banking payments data
SHARE ARTICLE
Share link copied!